Casino Affordability Checks UK 2026: Expert Guide
Table of Contents
What Are Casino Affordability Checks UK 2026?
Casino affordability checks is the popular name for the financial checks online casinos run on their customers. The Gambling Commission itself avoids the term: it says it has no regulatory requirements for affordability checks, and that calling its planned financial risk assessments an “affordability” check is inaccurate (UKGC). The rules that do exist follow the Government’s Gambling White Paper, published in April 2023. There are two separate measures, and only one of them is live today. Understanding the difference helps you know exactly what to expect from the casino affordability checks UK sites carry out.Financial Vulnerability Checks — Required Since 2024
Under licence condition SR Code 3.4.4, an online casino must run a financial vulnerability check when a customer’s deposits minus withdrawals exceed £150 in a rolling 30-day period. The threshold was £500 from 30 August 2024 and fell to £150 on 28 February 2025. The check is a public record search for significant signs of financial vulnerability: a bankruptcy order, a County Court Judgment (CCJ), an Individual Voluntary Arrangement (IVA), a High Court Judgment, an administration order or a Debt Relief Order, or an equivalent.
The check does not use credit reference data (UKGC) and needs no action from you. In its review of the first months, the Commission found that 78 percent of checks came back within 10 minutes, and that operators checked about 7 percent of their active accounts at the original £500 threshold (UKGC blog).
Financial Risk Assessments — Decided, Not Yet Live
Financial risk assessments are a different, more detailed form of casino affordability checks UK players may meet in future, using limited credit reference data. After a pilot, the Commission decided in July 2026 to introduce them in stages, starting with the largest operators and customers whose net deposits exceed £5,000 in a rolling 24 hours (£2,500 for under-25s). The start date for this first stage has not yet been confirmed (UKGC).
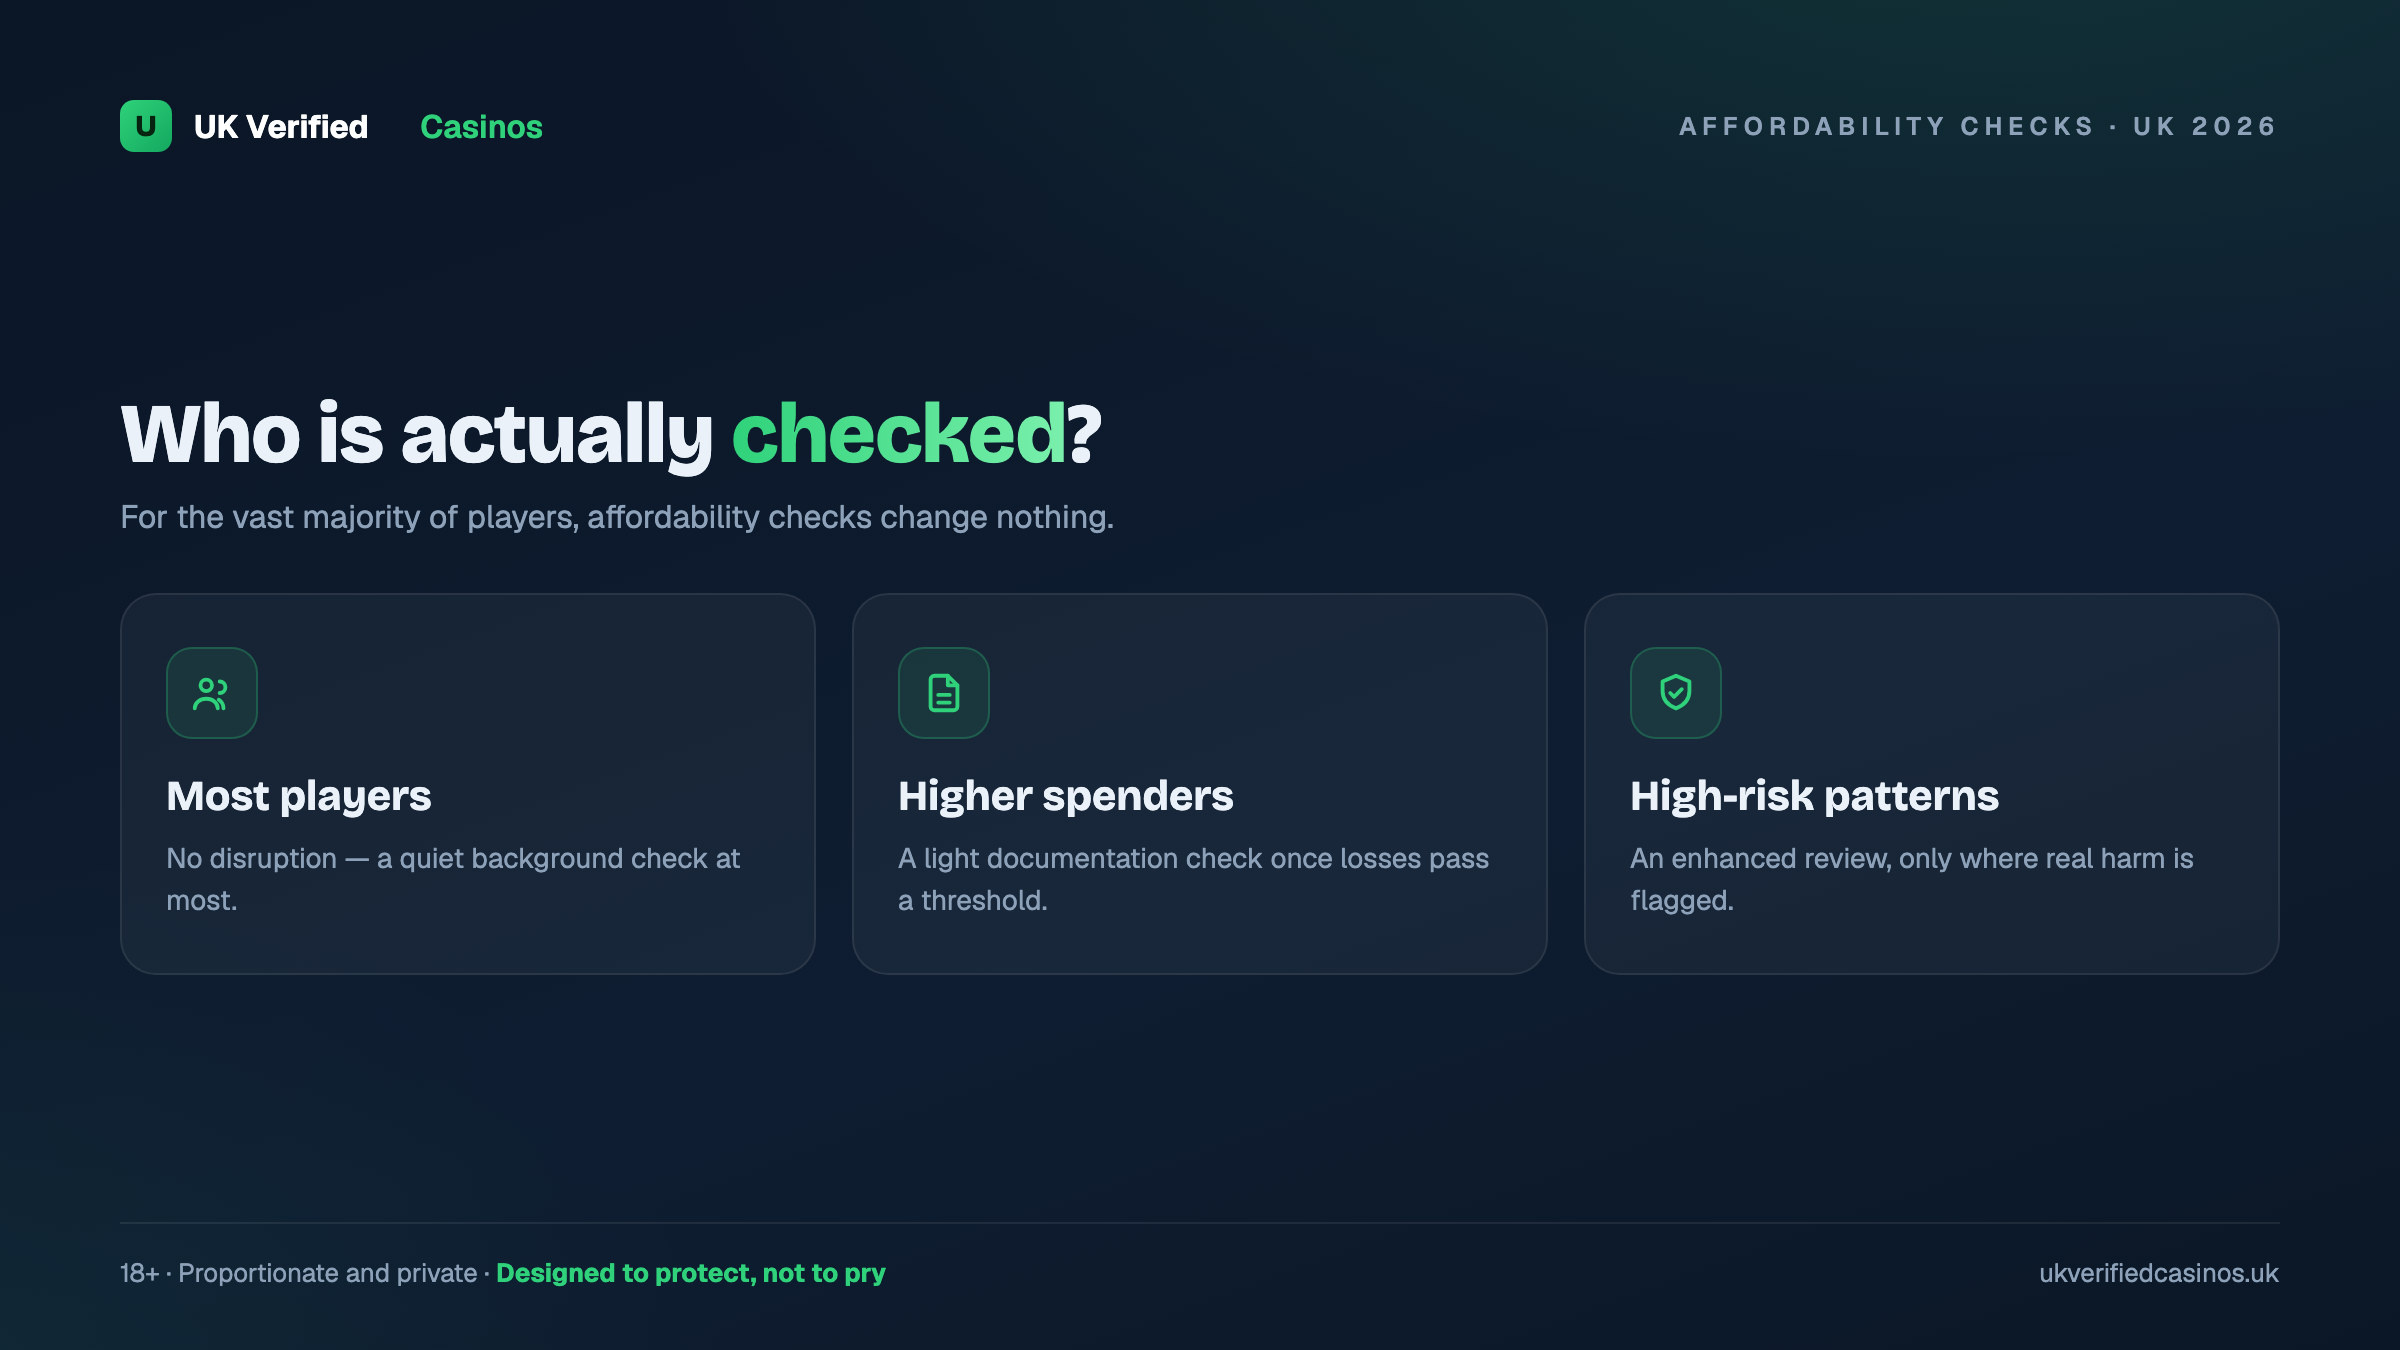
Once fully in place, they will apply to customers aged 25 or over with net deposits above £1,000 in a rolling 24 hours or £3,000 over 90 days, and to under-25s at £750 in 24 hours or £2,000 over 90 days. The UKGC says the assessments will be document-free for almost everyone, will not affect your credit score, and that fewer than 3 percent of accounts would need one.
For a broader overview of the regulatory landscape governing these rules, see our detailed guide to UK casino regulations 2026.What Triggers an Affordability Check?
Casino affordability checks under today’s rules are triggered by net deposits over a rolling period, not by how much you wager. Net deposits are your deposits minus your withdrawals with that casino. The current triggers are:- Net deposits above £150 in a rolling 30 days — the casino must run a financial vulnerability check (since 28 February 2025).
- No repeat check within 12 months — a casino does not have to run the check again at the threshold if it already ran one, or a financial risk assessment, in the previous 12 months.
Casinos can also check earlier: the Commission found that 36 percent of operators ran the check at earlier points, such as registration or first deposit (UKGC blog). After a check, the casino must consider the result together with everything else it knows about you, take proportionate action when it identifies risk, and record why (SR Code 3.4.4).
It is worth noting that the casino affordability checks UK operators run are separate from standard KYC identity verification. All online gambling businesses must check your age and identity before you gamble, often by matching your details against credit reference agency and electoral roll records (UKGC). Identity checks confirm who you are; a financial vulnerability check looks for signs of serious financial difficulty.
Your Documents and Your Rights
When casino affordability checks UK raise questions, or a casino runs its anti-money-laundering checks, it may ask you for information. Knowing why, and what you can do if you disagree, protects you as a player.Documents a Casino Can Legitimately Request
The Gambling Commission does not set a list of documents casinos must ask for. For identity, it says businesses can ask for items such as passports, driving licences and household bills (UKGC). For financial questions, it explains that casinos may ask for:- Bank statements — to check that your source of funds is legitimate, as part of anti-money-laundering checks
- Information about irregular income — for example, a pending house sale
- Open banking data or documents — for the small number of accounts a financial risk assessment cannot cover, once those assessments start
Your Rights During Casino Affordability Checks UK
You retain important rights throughout casino affordability checks. These include:- Right to a manual review — if a casino acts on a financial vulnerability check through a fully automated decision, it must offer you the opportunity of a manual review (SR Code 3.4.4).
- Right to complain — complain to the casino first; it has 8 weeks to resolve your complaint (UKGC).
- Right to free ADR — if you are still unhappy after 8 weeks, you can take the dispute to a free, independent Alternative Dispute Resolution (ADR) provider (UKGC).
- Right to data protection — documents you provide are covered by UK data protection law.
Do These Checks Affect All Players?
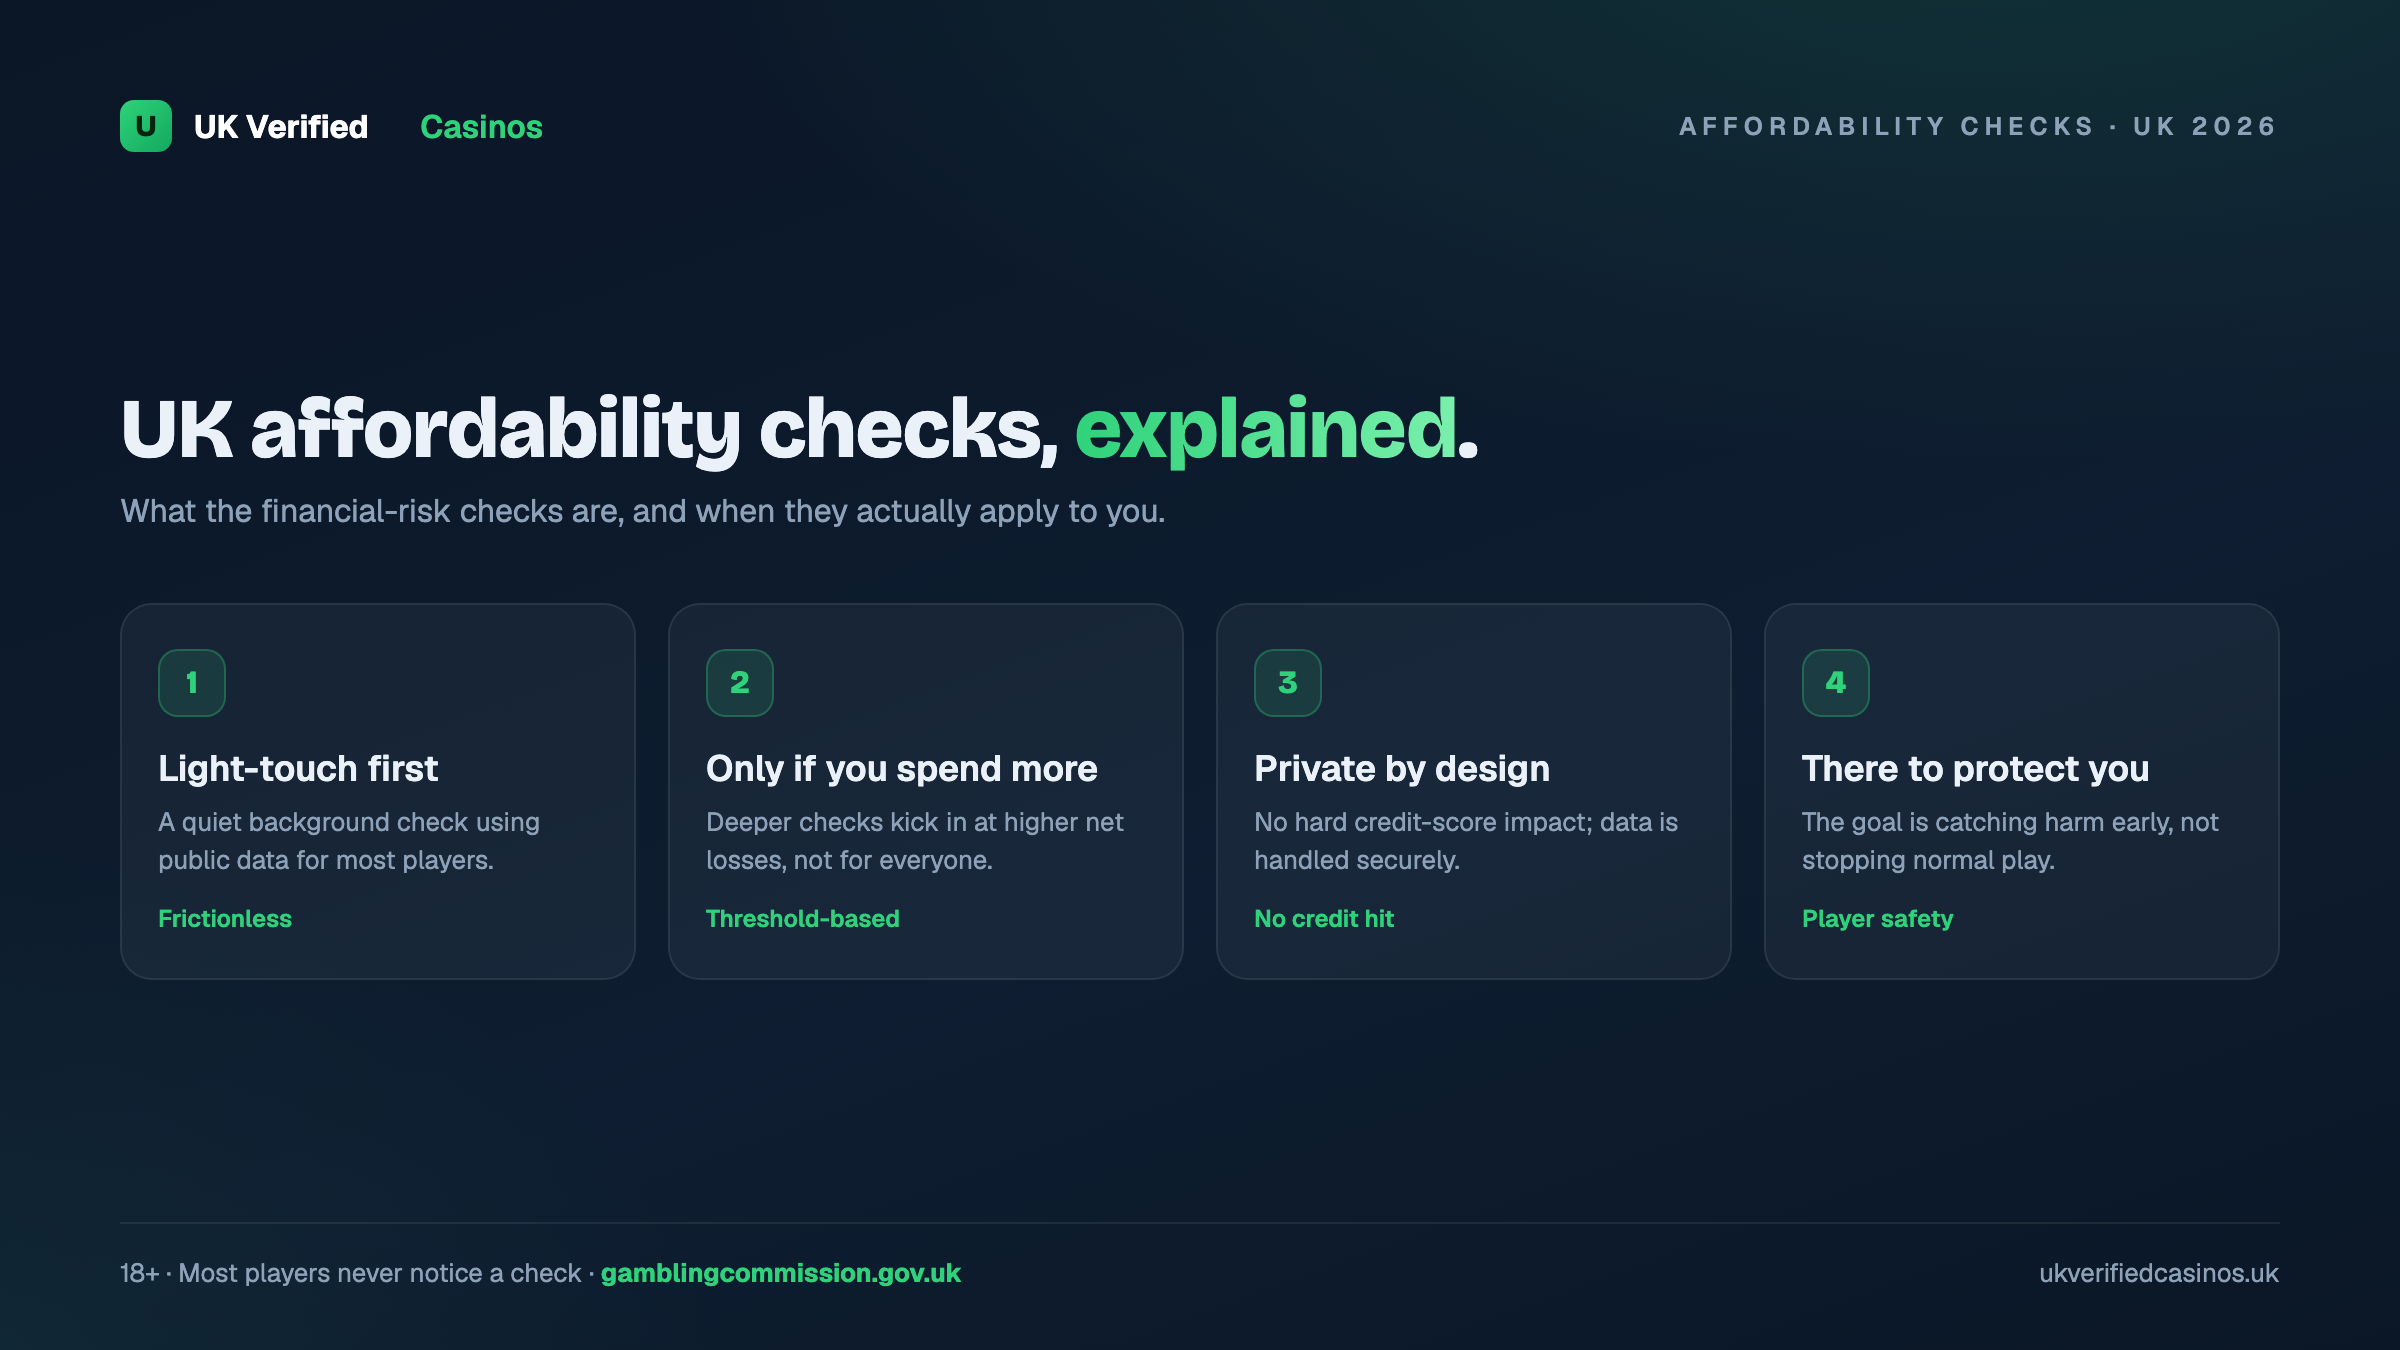
Most UK players will rarely notice the casino affordability checks UK casinos carry out. A financial vulnerability check only becomes compulsory once net deposits pass £150 in a rolling 30 days, it runs in the background, and the Commission’s review found most checks came back within minutes. If the public record search finds nothing, you may never know it happened.
If a check does flag something, such as a single CCJ, the Commission has reminded operators that they are not required to use automated measures that add significant friction, such as stopping an account, where the risk may be lower (UKGC blog). Under the casino affordability checks UK rules, the response should be proportionate to the risk.
For related topics, see our guides to best casino bonuses UK and fast withdrawal casinos UK.
| Check Type | Trigger Threshold | Method | Player Action Required? | Possible Outcome |
|---|---|---|---|---|
| Financial vulnerability check | Net deposits over £150 / rolling 30 days (since 28 February 2025) | Public record search (bankruptcy, CCJ, IVA, DRO and similar) | No | Proportionate action if risk is found; manual review offered after automated decisions |
| Anti-money-laundering (source of funds) | Risk-based, decided by the casino | Information such as bank statements | Yes, if asked | Casino may be unable to let you keep gambling without it |
| Financial risk assessment (not live yet) | Stage 1: net deposits over £5,000 / 24 hours (£2,500 under 25) | Limited credit reference data; document-free for almost everyone | No | Start date to be confirmed by the UKGC |
| ADR complaint route | N/A | Free, independent dispute resolution after the casino’s 8-week complaints process | Player-initiated | N/A |
| UKGC enforcement | N/A | Regulator oversight of licensed casinos | No | Casino may lose licence |
Sources: UKGC SR Code 3.4.4, financial risk assessments decision (7 July 2026) and ADR guide.
Affordability Checks and Responsible Gambling
If you are concerned about your spending, the casino affordability checks UK rules require are only one layer of protection available to you. You can also proactively use a casino’s responsible gambling tools, such as deposit limits, loss limits, session time limits and cooling-off periods, which UKGC-licensed casinos offer in their account settings.
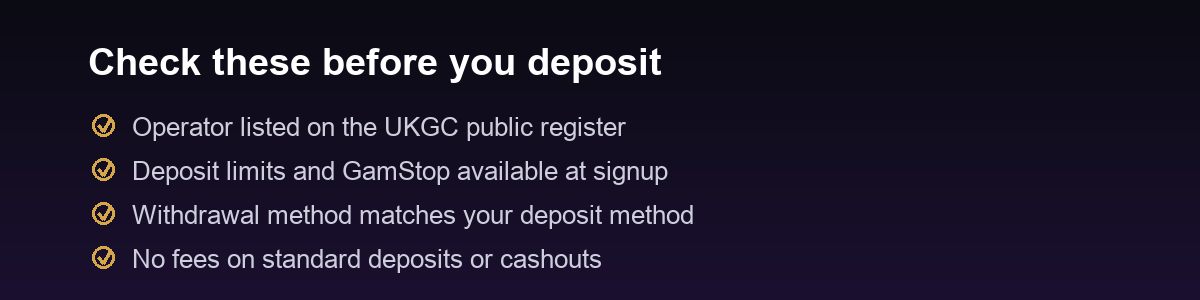
For players who need a stronger measure, the GamStop self-exclusion scheme lets you block yourself from all UKGC-licensed casinos simultaneously with a single registration. This is completely free and takes effect quickly across every licensed UK operator.
Understanding casino affordability checks UK alongside tools like what is RTP in slots and our responsible gambling UK guide gives you a complete picture of your rights. Players who use all available tools make better-informed decisions about how they play.
Frequently Asked Questions
Q: What are casino affordability checks UK and are they mandatory? A: Casino affordability checks UK are not a regulatory requirement: the Gambling Commission says it has none. Since 28 February 2025, casinos must instead run a light-touch financial vulnerability check, using publicly available data, once net deposits exceed £150 in a rolling 30 days, in line with the Government’s Gambling White Paper (April 2023).
Q: What triggers casino affordability checks UK — how much can I lose before a check happens? A: Casino affordability checks UK are triggered by net deposits (deposits minus withdrawals), not by losses or wagering. Since 28 February 2025, a casino must run a financial vulnerability check once your net deposits exceed £150 in a rolling 30-day period. Casinos may also check earlier, for example at registration or first deposit.
Q: What documents can a casino request during casino affordability checks UK? A: During casino affordability checks UK, a financial vulnerability check needs no documents: it is a public record search. Separately, a casino may ask for bank statements to check your source of funds as part of anti-money-laundering checks, or for information about irregular income such as a pending house sale. The Gambling Commission does not set a fixed list of documents.
Q: What are my rights when casino affordability checks UK are applied to my account? A: If a casino acts on a financial vulnerability check through a fully automated decision, it must offer you a manual review. You can complain to the casino, which has 8 weeks to resolve your complaint, and then take the dispute to a free, independent ADR provider. Documents you share are covered by UK data protection law.
Q: Do casino affordability checks UK affect casual or low-stakes players? A: For most players, casino affordability checks UK mean one background check: a financial vulnerability check only becomes required once net deposits pass £150 in a rolling 30 days, and it runs in the background using public records. Financial risk assessments, once introduced, start at much higher spend levels, and the UKGC says fewer than 3 percent of accounts would need one when fully implemented.
Q: Can a casino restrict my account because of casino affordability checks UK? A: Yes. If casino affordability checks UK show risk, the casino must take proportionate action, which can include limits on your account. The UKGC has told operators they do not have to stop an account automatically over a single CCJ where the risk may be lower. If you do not provide information needed for identity, anti-money-laundering or safer gambling checks, the casino may not be able to let you keep gambling.
Q: Where can I get help if I am struggling with gambling beyond what casino affordability checks UK can address? A: Contact GamStop to self-exclude from all UKGC-licensed casinos simultaneously. You can also use in-casino responsible gambling tools such as deposit limits, loss limits, and cooling-off periods. Our responsible gambling UK guide covers all available support options in detail.